Where this sits: We expected the filing to show a lab living on other people's money. On the numbers, it shows a careful custodian of it.
ChartSpaceX 424B4 and 10-Q; Anthropic S-1
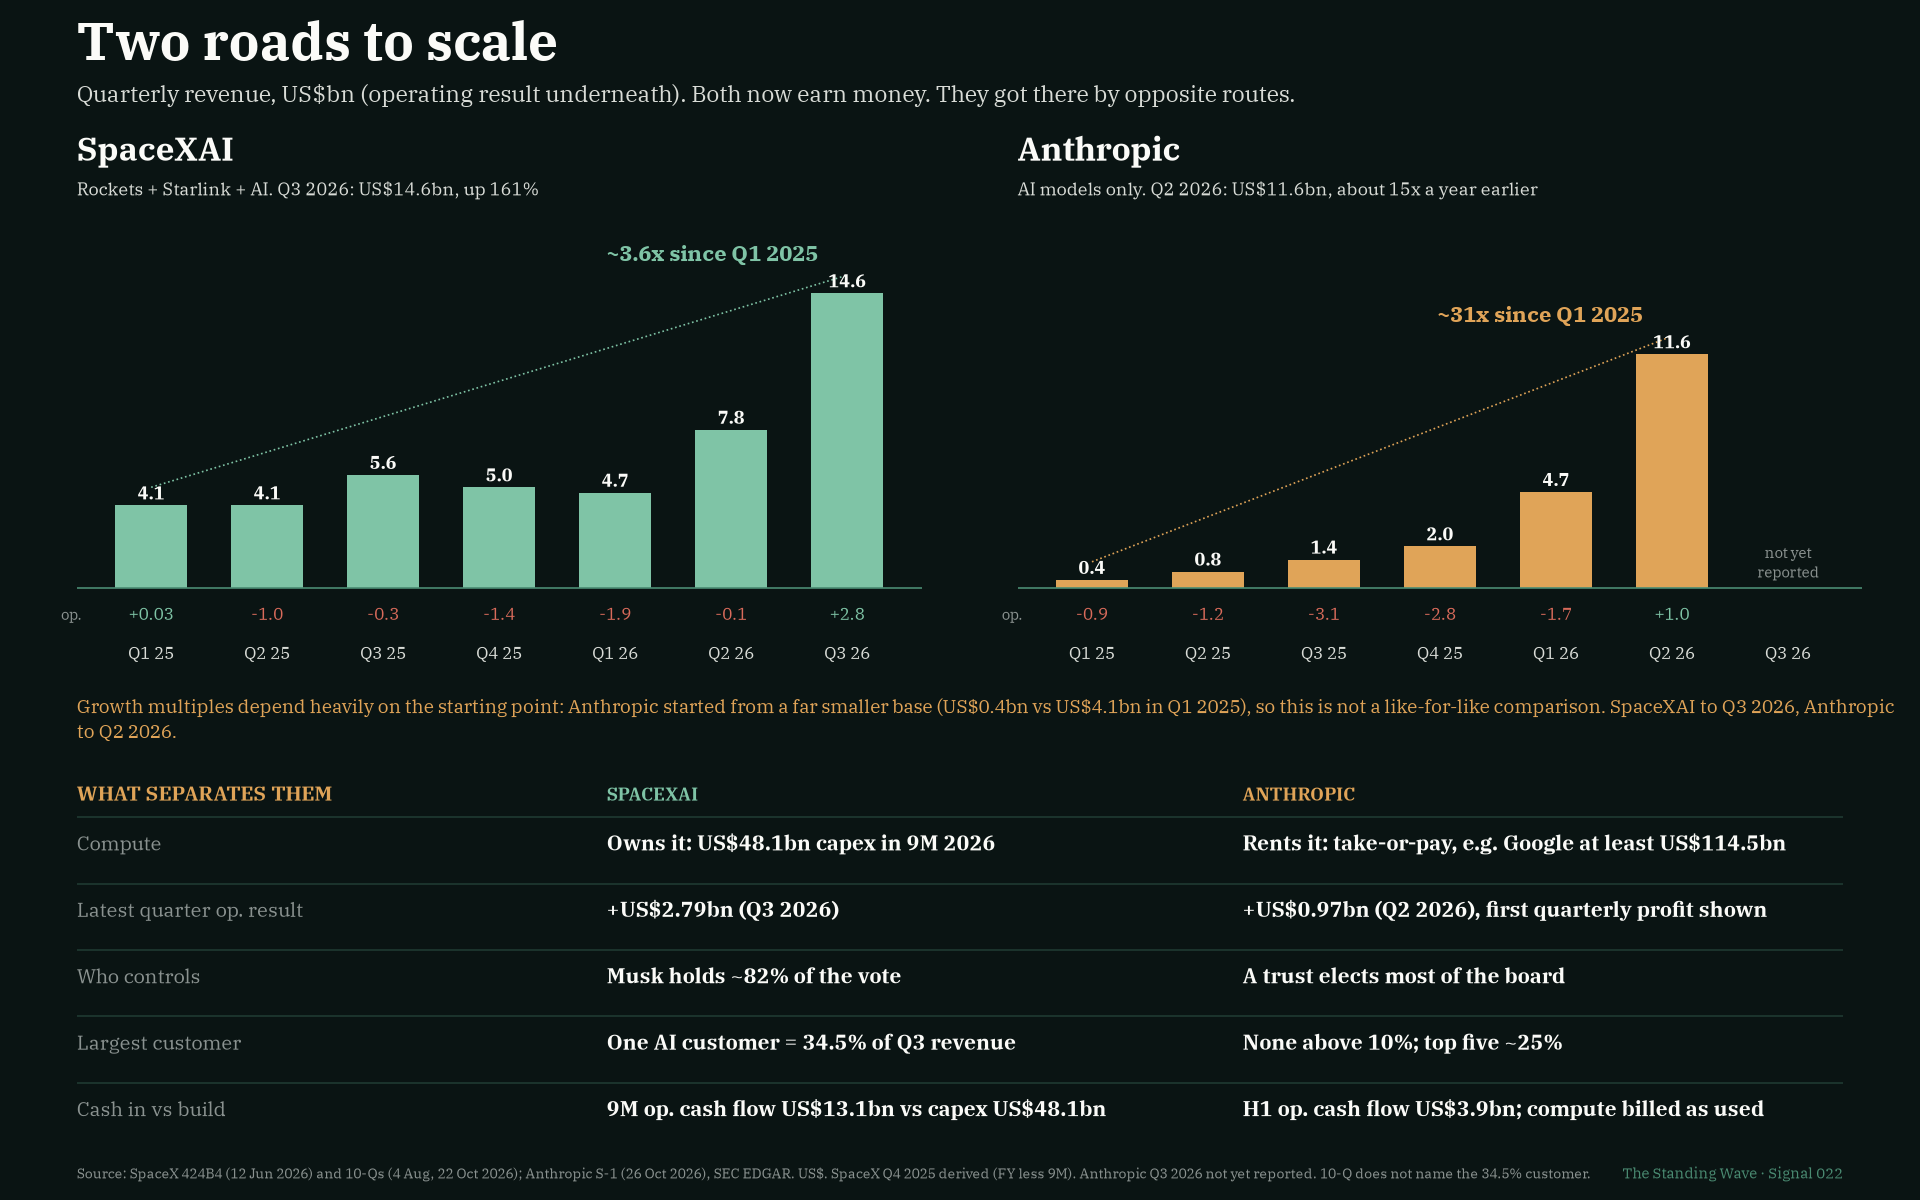
Two roads to scale
SpaceXAI owns its computing; Anthropic rents it on long contracts. Since early 2025 quarterly revenue grew about 31-fold at Anthropic and 3.6-fold at SpaceXAI, from very different bases.
Quarterly revenue, US$ billions. No Anthropic third quarter yet.
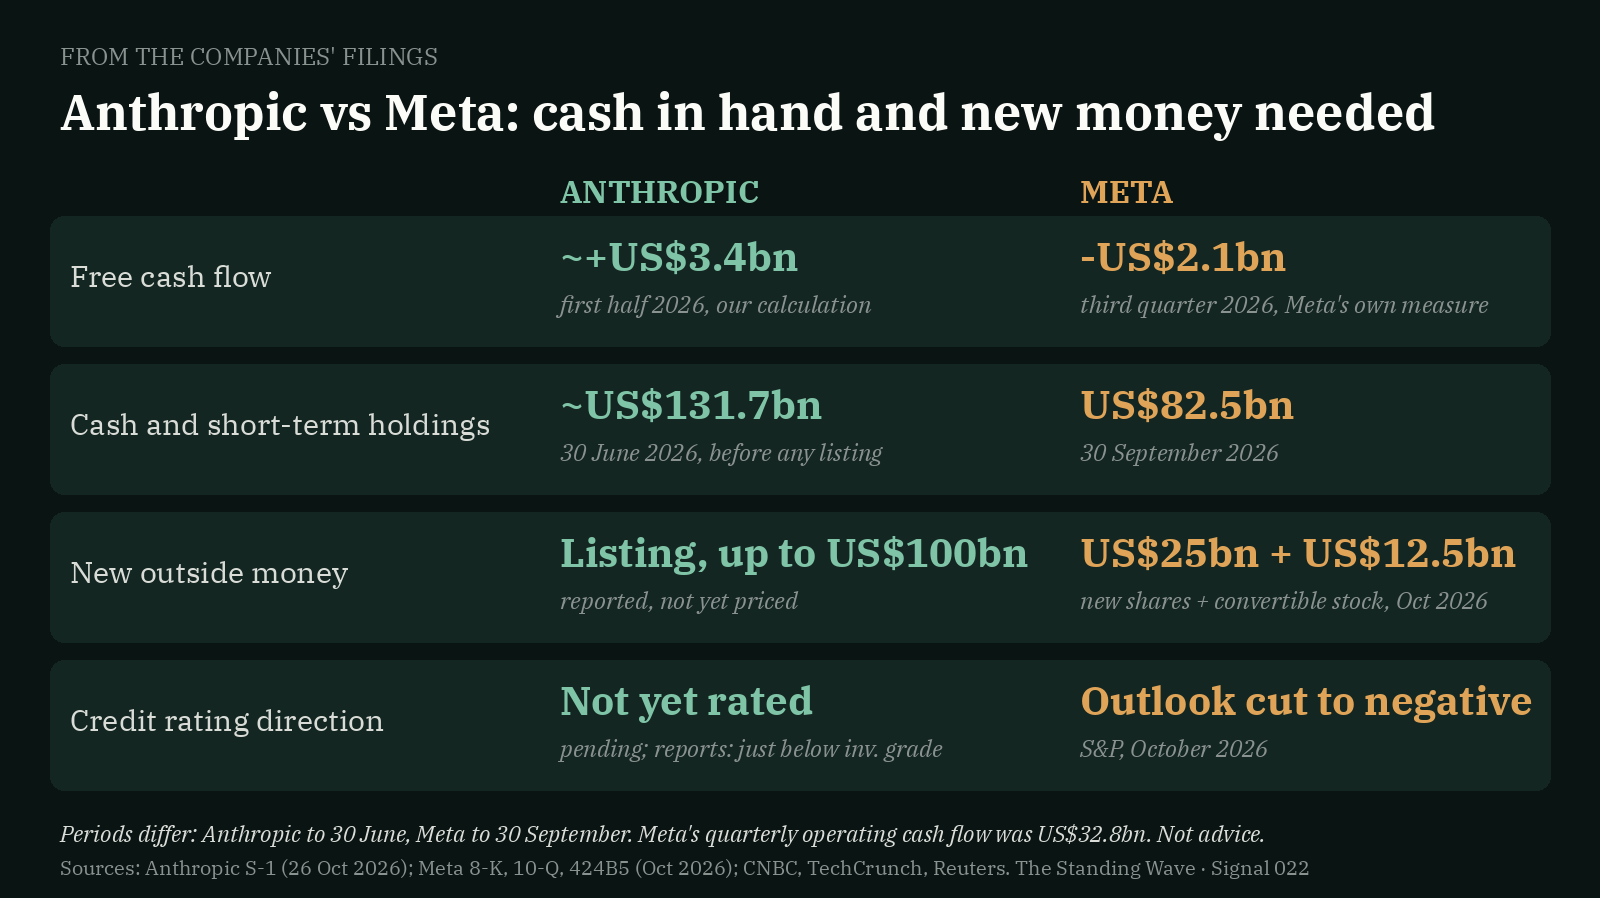
Compare Meta, after a far longer run. Its free cash flow was negative US$2.12 billion last quarter, on its own measure. It is selling 40 million new shares at US$625 and US$12.5 billion of convertible stock, S&P moved its outlook to negative citing "elevated capital expenditures and future cash flow", and it has US$355.73 billion of leases not yet started. Meta still took in US$32.79 billion of operating cash in the quarter. It is building, not failing.
Our honest score: Anthropic looks better than we expected. We were partly wrong on the edge too: the first rating warning went to a giant. Anthropic's own credit rating is still to come; early reports point to just below investment grade, and we will score that when the agencies publish.
ChartAnthropic S-1; Meta 8-K, 10-Q, 424B5
Anthropic vs Meta
Anthropic holds more cash and its free cash flow is positive; Meta earns far more but spent more than it made last quarter and is selling new stock.
Periods differ. Anthropic free cash flow is our calculation; Meta's is its own measure.
Why list at all? Because the private cheques got too big to write. In Signal 004 on 9 June we wrote: "That is what a capital top looks like: not a crash, but the moment the cheque gets too big for the people who used to write it." Anthropic has raised US$141.1 billion privately, with US$431 billion of computing deals that cannot be cancelled, IFR reports. The counter: a US$65 billion private round in May shows the cheques have not stopped yet, and a listing also lets early backers and staff sell.
ChartAnthropic S-1
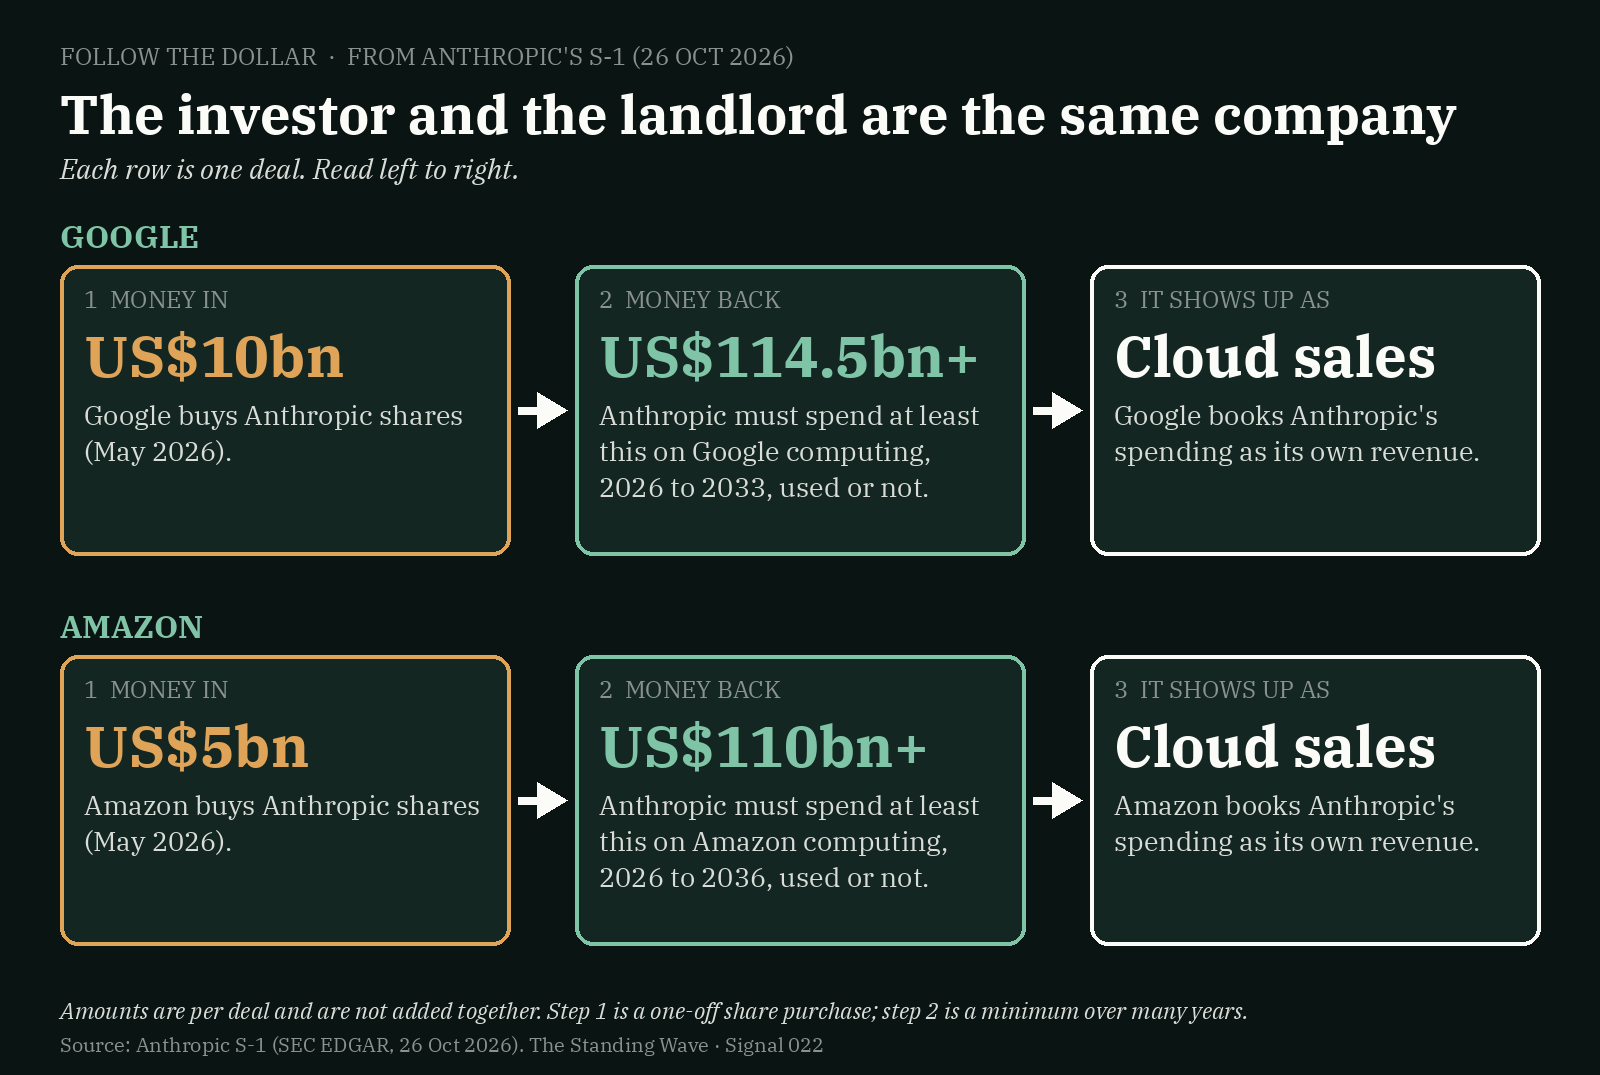
Follow the dollar
Google and Amazon put money into Anthropic, Anthropic promises to spend far more on their computing, and that spending becomes their cloud revenue.
Each row is one deal; amounts are not added together.
The filing's boldest claim is that knowledge work was worth "more than $40 trillion in economic value globally in 2025". We find that questionable as a market size, but the runway is long. It also says "each new version of a Claude model directly accelerates development of the next". Our view, not the filing's: if better models keep cutting the cost of building the next one, margins should keep widening. The filing does not prove it.
Price: Reuters reports a raise of up to US$100 billion, with some investors at about US$1.5 trillion, down from roughly US$2 trillion expected earlier. That is about 32 to 43 times the latest quarter's revenue times four, our rough sums. On these numbers, the range looks defensible to us, given the cash in hand and the cash coming in. The counter: the third quarter is blank, 43 times prices in growth not yet delivered, and the edge contracts can still bite. SpaceX listed at about 95 times last year's revenue and now sits near 31 times; in our view the price it listed at was steep. This is our view, not advice.
Our view on OpenAI: it is now in a race against time to put its own numbers in public. Anthropic has set the bar with a full filing, while OpenAI has cut its private round target to US$20 billion from about US$30 billion, CNBC reports. If OpenAI does not match it, that silence is a tell, and the question goes back to trust.
Our read: a strong centre, a well-funded lab, and an edge whose risk sits in contract terms, not yet defaults.
What it means for youwhen a company asks for your money, read its cash flow statement before its vision statement.
What to watchAnthropic's price range, safe-company borrowing costs, and any customer giving notice to SpaceX or a neocloud.